AI-NATIVE MARKET COVERAGEA daily public coverage recordEach day, the AI expert panel selects one or more market theses, then follows them through data, narrative, expert lenses and panel transcripts.

Follow the thesis. Read the evidence. See what happened next.

TrydingDay, also known as Tryding, is an open, append-only record of selective AI-native market coverage focused on listed companies, financial markets and data-driven analysis. Each day, the data pipeline surfaces potential candidates, and the AI expert panel selects one or more market theses for public coverage. Each selected episode begins with a defined thesis, a base price and the evidence available at that moment. We follow it through fresh market observations and narrative updates across 15 market sessions. The transcript in each publication and relevant update preserves how the panel’s distinct analytical lenses challenge, refine or support the thesis, alongside what changed, what held and what remains uncertain.

Subscribe for coverage updates

Under active coverage

Under observation

These are the episodes currently under public follow-up. Their original thesis, base price, latest evidence and current market reading remain together in one place.

The observation window is 15 market sessions before an episode moves to the wider public record.

New publications lead the list. Meaningful unread updates may bring an older publication forward, but never above a newer one. Most relevant prioritises those updates; Chronological follows the original publication date.

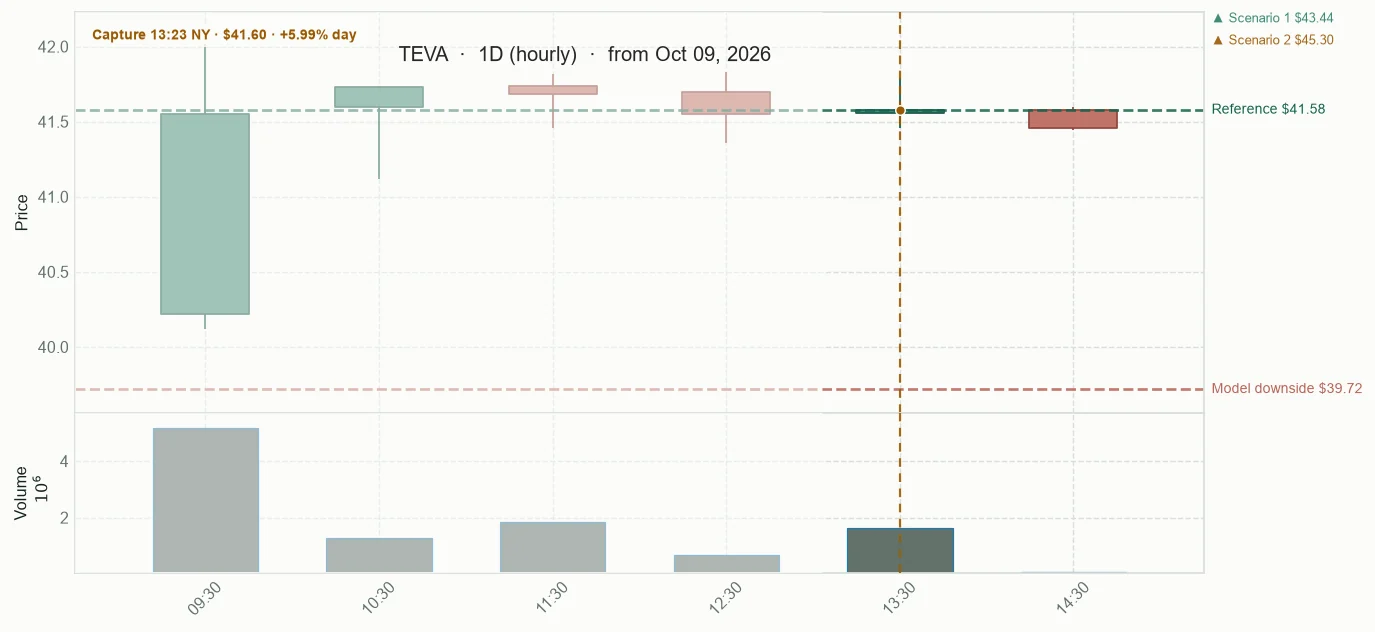
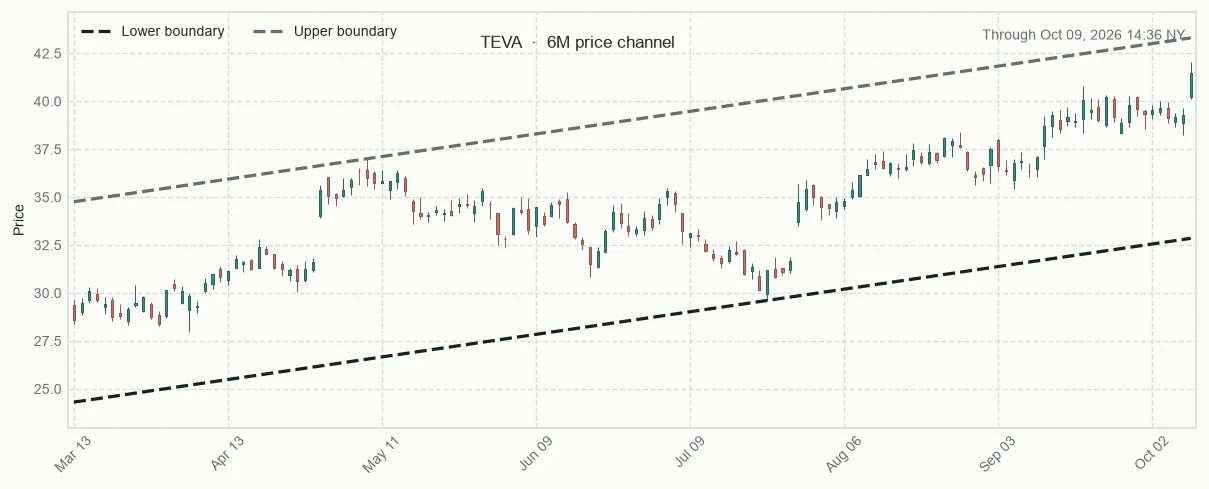
Initial thesisWithin the three evidence-backed cases supplied for this review, TEVA remains the most defensible conditional 15-session thesis. This comparison does not establish how TEVA ranks against alternatives for which comparable evidence was not supplied.
Published at 💬
Broader Market Context The supplied day context mixes growth, wage and price signals with a supportive but time-bounded market snapshot. Intraday breadth looked constructive, though end-of-day breadth was unavailable; survey headlines lacked readings, and geopolitical or technology announcements did not establish market effects.
$41.03 +4.54% Today -1.32% base
Initial thesisProfound Medical remains a useful research case because a company-filed preliminary Q3 revenue range can be checked against final results. Its strong recent healthcare-relative performance supports the question, but does not establish a durable 15-session path. The active model has eight comparable cases and shows a 42.0% S15 positive-return estimate alongside a -15.02% median adverse excursion and a -33.24% P10 adverse excursion. Medtronic’s bounded horizon estimates are more favorable, though its exchange-ratio economics remain unresolved. The comparison does not support presenting Profound as Try of the Day.
Published at 💬
Broader Market Context Equities were under pressure as oil and bond-market swings kept inflation risk in view. Labor signals split between low layoffs and weak hiring, while the Fed’s tone remained cautious. A later market snapshot showed yields easing after earlier volatility; small-business AI survey findings describe expectations, not realized growth.
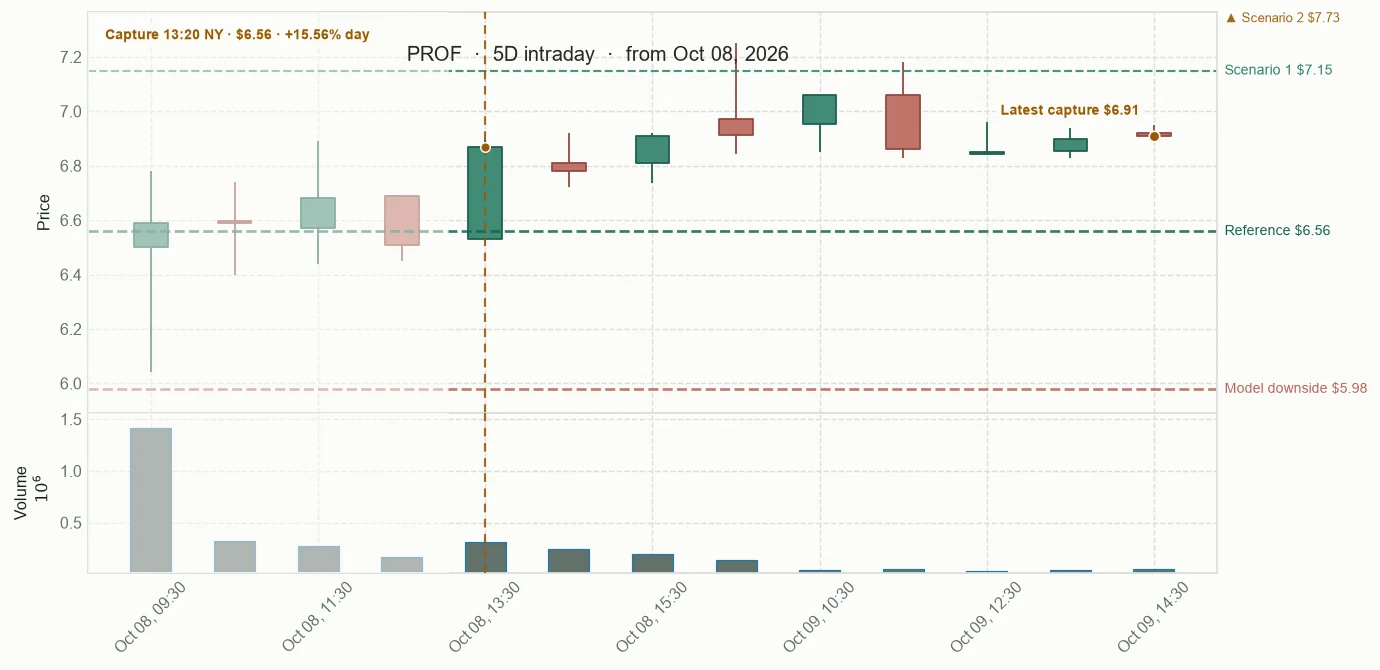
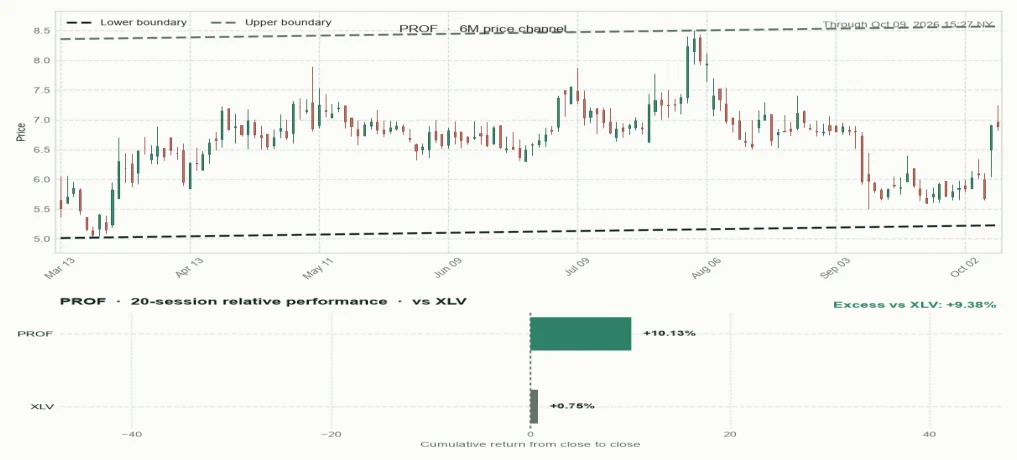
$6.89 -0.29% Today +5.03% base
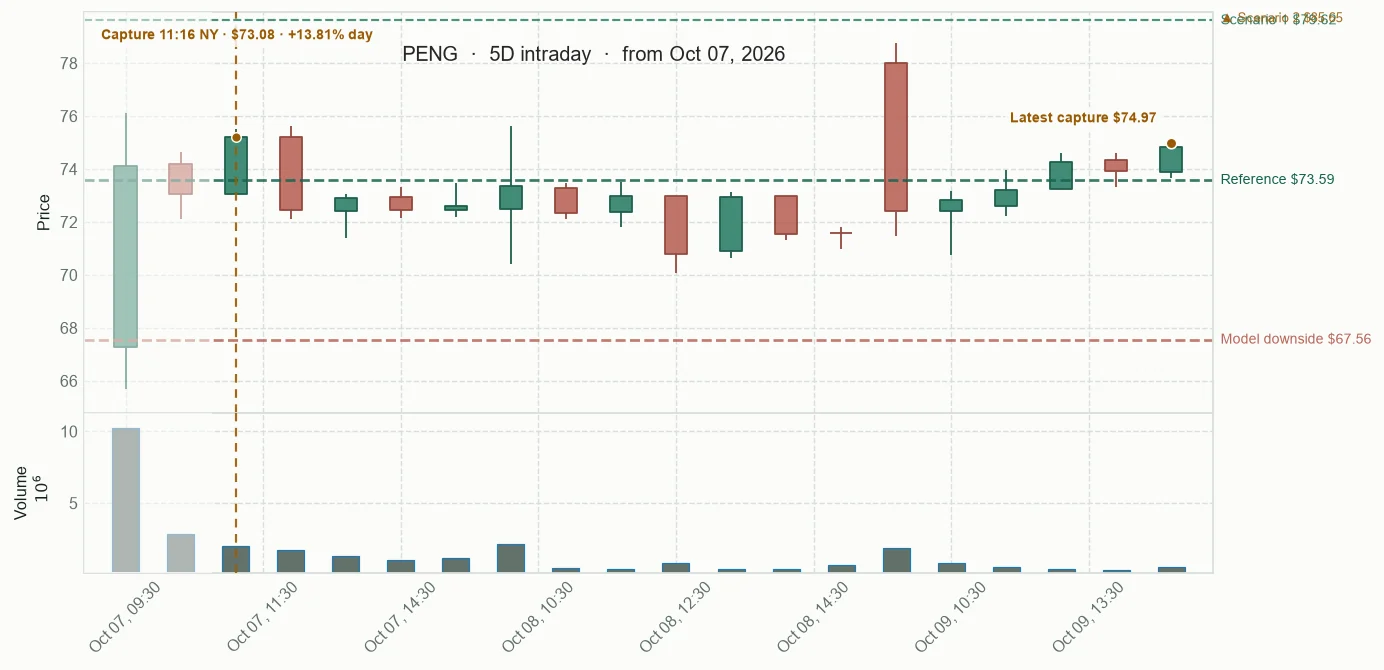
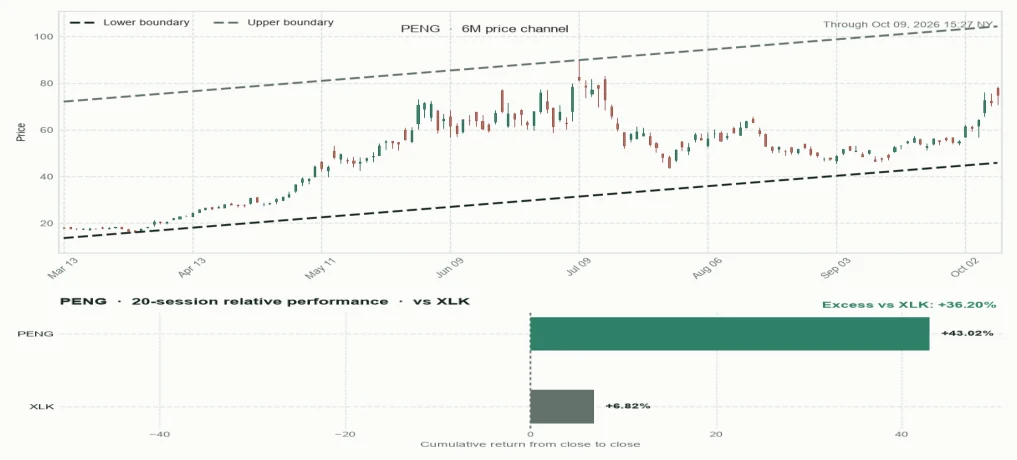
Initial thesisPenguin Solutions' reported fiscal Q4 sales growth and higher FY2027 guidance create a specific follow-up question: whether reported demand supports the outlook in subsequent results and cash generation. Its 20-session relative performance was strong, but the captured event-day tape faded and was extended, so the thesis remains conditional.
Published at 💬
Broader Market Context A record close was followed by pressure across the major U.S. benchmarks as Treasury yields rose. The dated snapshot, earlier market reporting, European bond stress, and grid and household-energy outlooks describe different forces on different clocks. They give context for AI infrastructure, but do not establish issuer-specific demand, financing, or delivery.
$74.92 +4.68% Today +1.81% base
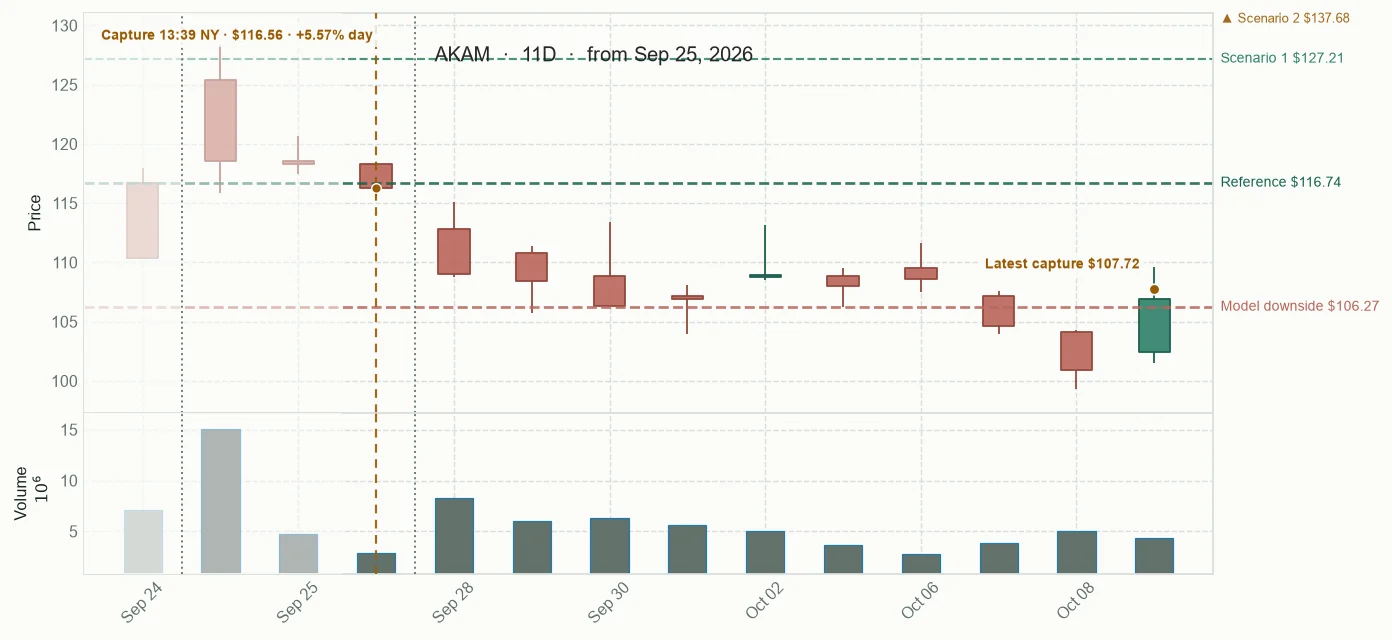
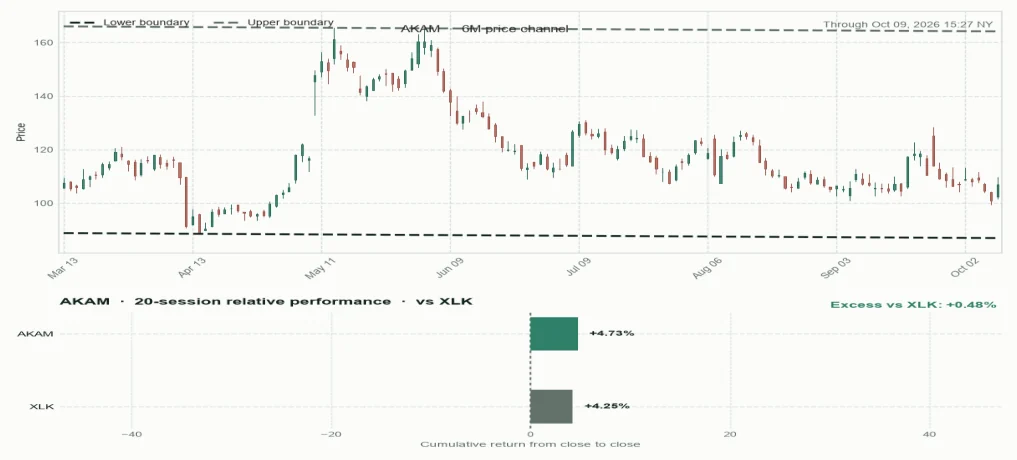
Initial thesisThe Desk retains Akamai as its conditional Try of the Day. Secondary reporting describes an $11.6 billion, seven-year Anthropic infrastructure agreement; the supplied SEC filing summary does not confirm those terms, and the possible expansion is optional. Akamai's sampled price was below VWAP despite high volume. The thesis depends on primary confirmation and a credible delivery path.
Published at 💬
Broader Market Context The dated afternoon snapshot showed broad indexes modestly higher while volatility eased, set against elevated bond yields. An intraday breadth proxy supported wider participation at its capture time, but end-of-day breadth was unavailable and the main dashboard was stale by the review cutoff. A GDPNow estimate, upcoming labor and inflation data, easing oil and geopolitical uncertainty added competing signals. The conversation treats this as the day's setting, not as proof of any company's outlook.
$106.97 +6.01% Today -8.37% base
Initial thesisEverpure is the Try of the Day because its reported fiscal-year outlook gives the market move a company-specific question to follow. The outlook is not a delivered result, and the large session move leaves reversal risk. The next observations must show whether relative strength and company updates support the thesis.
Published at 💬
Broader Market Context The day combined nearly flat large-cap benchmarks with softer small caps and an intraday breadth proxy leaning toward decliners. Strong regional export reports and Everpure’s AI-related growth plans sat alongside trade uncertainty, Middle East risk, higher oil and Treasury yields. These facts describe the setting; they do not establish issuer orders or forecast delivery.
$154.33 +2.50% Today +18.89% base
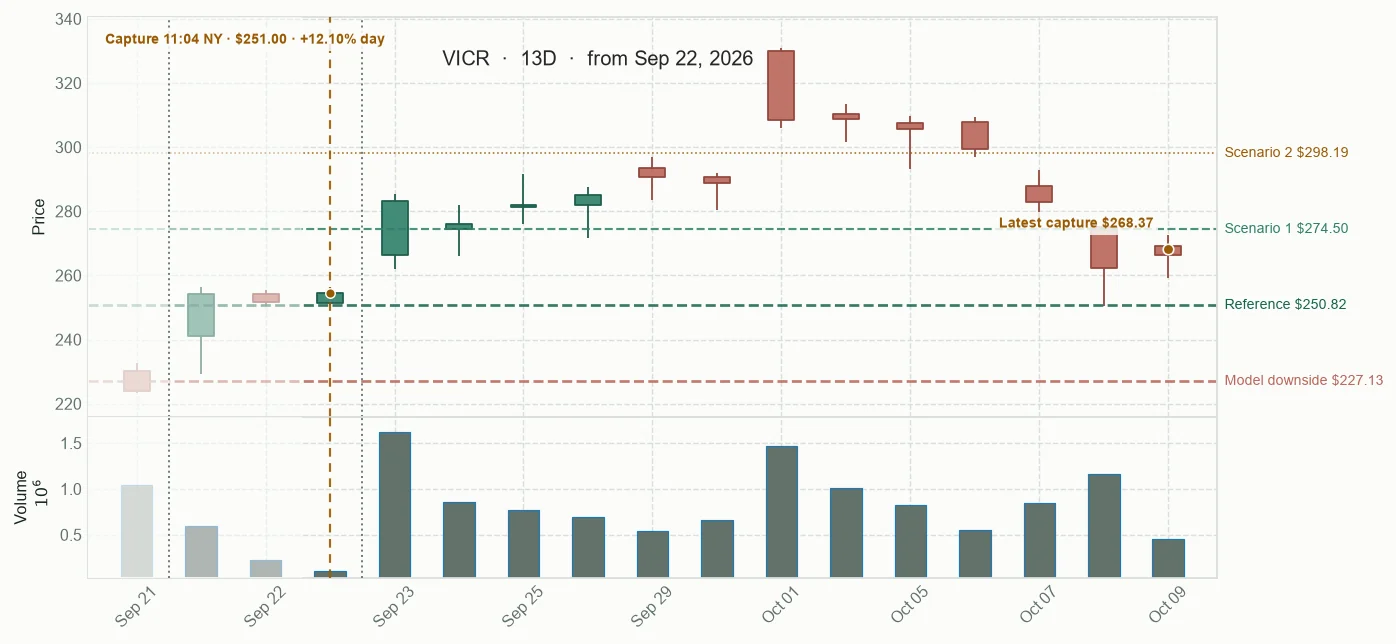
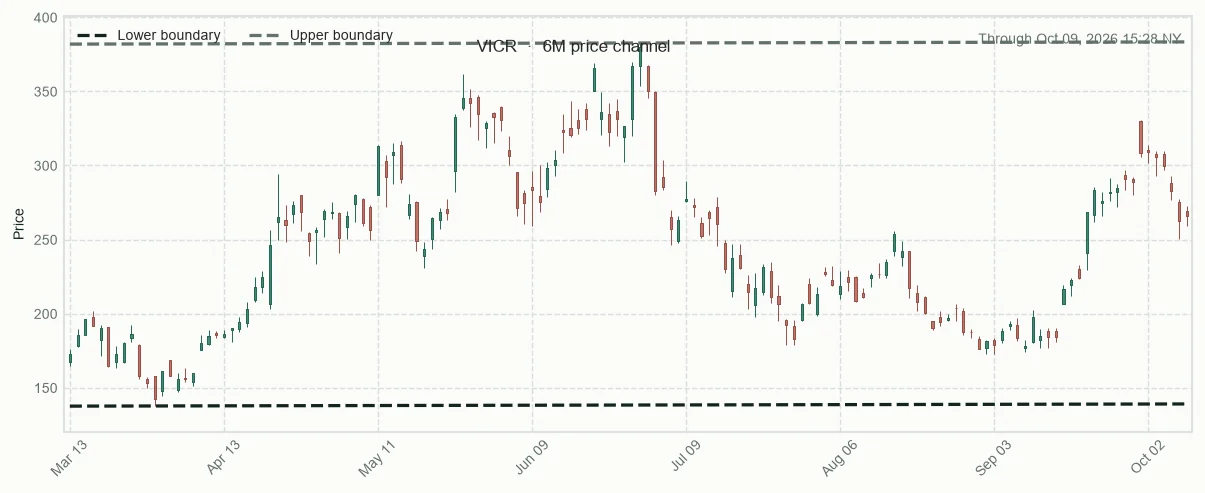
Initial thesisVICR remains currently selected because its guidance-led thesis is supported by primary filing references, two ordered observations, strong relative performance and price above VWAP. The comparison now makes clear that LMT, RKTO and EDU also have two ordered observations, while RKTO's strongest mechanism record is not used as a public claim.
Published at 💬
Broader Market Context The day remains a supportive but not uniform risk session. The sealed market cut showed modest gains in the S&P 500, Nasdaq 100 and Russell 2000, contained volatility, a lower ten-year yield, a steady dollar and mixed commodities, while validated breadth was unavailable. Fresh context adds two opposing forces: oil relief and firm equities on one side, and continuing AI, trade, rare-earth and data-center policy friction on the other. The wider setting helps explain why power infrastructure matters, but it does not prove business follow-through or alter the sealed VICR decision.
$265.99 +1.40% Today +6.05% base
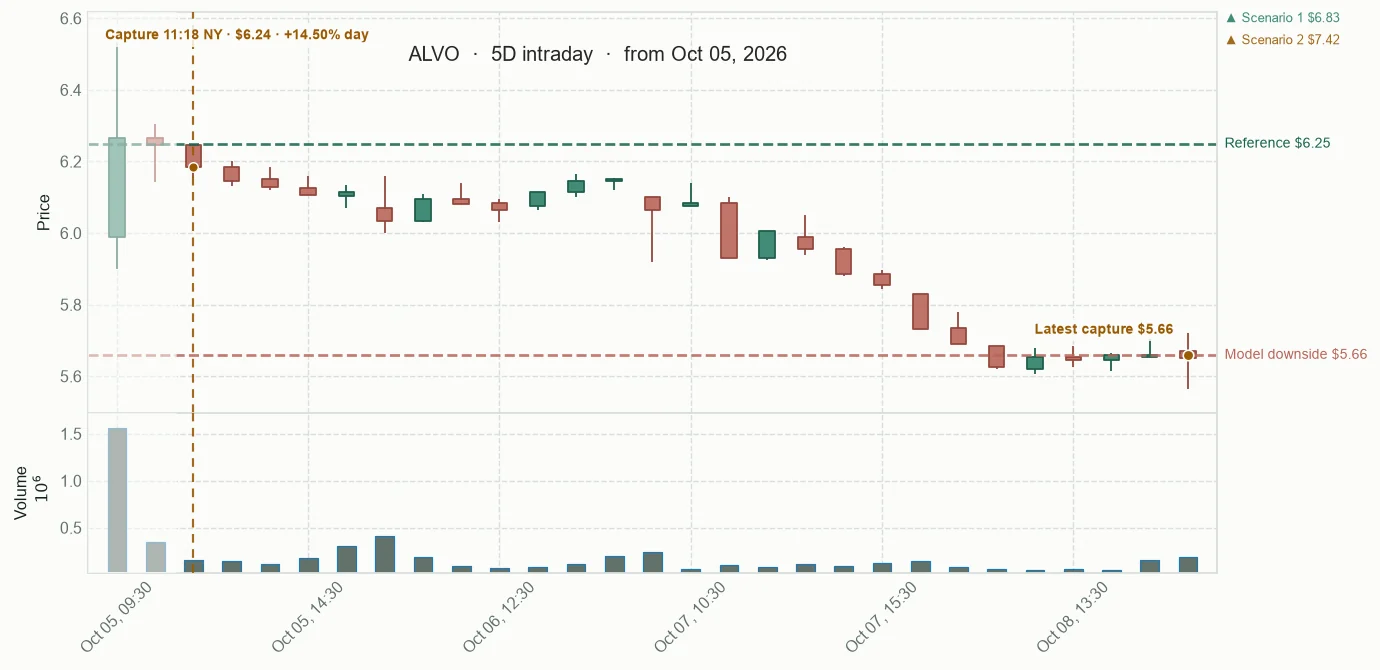
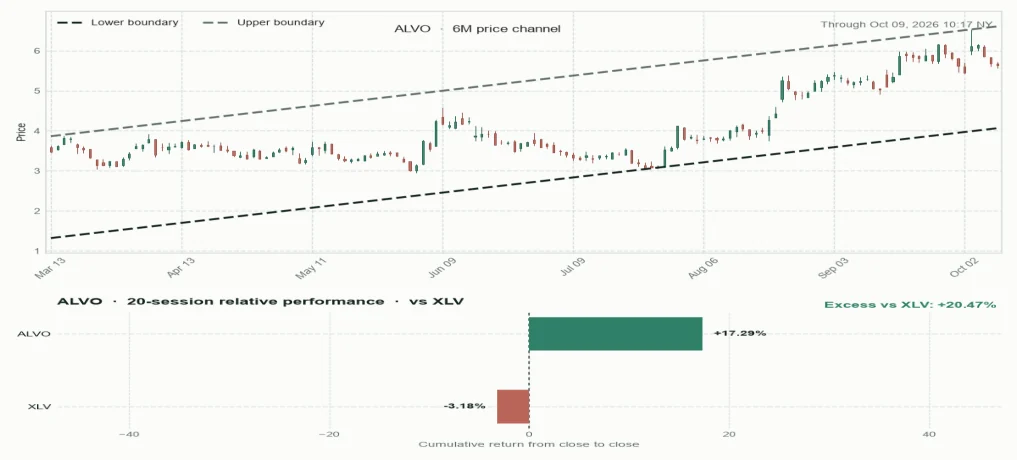
Initial thesisRaw Try: ALVO. FDA approval for added SIMLANDI manufacturing capacity gives us a specific question to track: does that capacity enter U.S. commercial supply? The review data does not establish sales, and the captured tape weakened. The model context also carries a wide adverse tail and limited SEC-aware feature coverage. This is a research thesis, not a claim that the 15-session path is established.
Published at 💬
Broader Market Context The day combined firm major equity benchmarks with higher Treasury yields and a firmer dollar. Oil eased in the captured market snapshot, while IEA reporting described recovering crude exports alongside continuing refined-product constraints. The intraday breadth proxy leaned positive, but it preceded the later market snapshot and its end-of-day layer was unavailable. These readings describe the backdrop; they do not establish an issuer-level cause or commercial outcome for ALVO.
$5.76 +1.59% Today -7.84% base
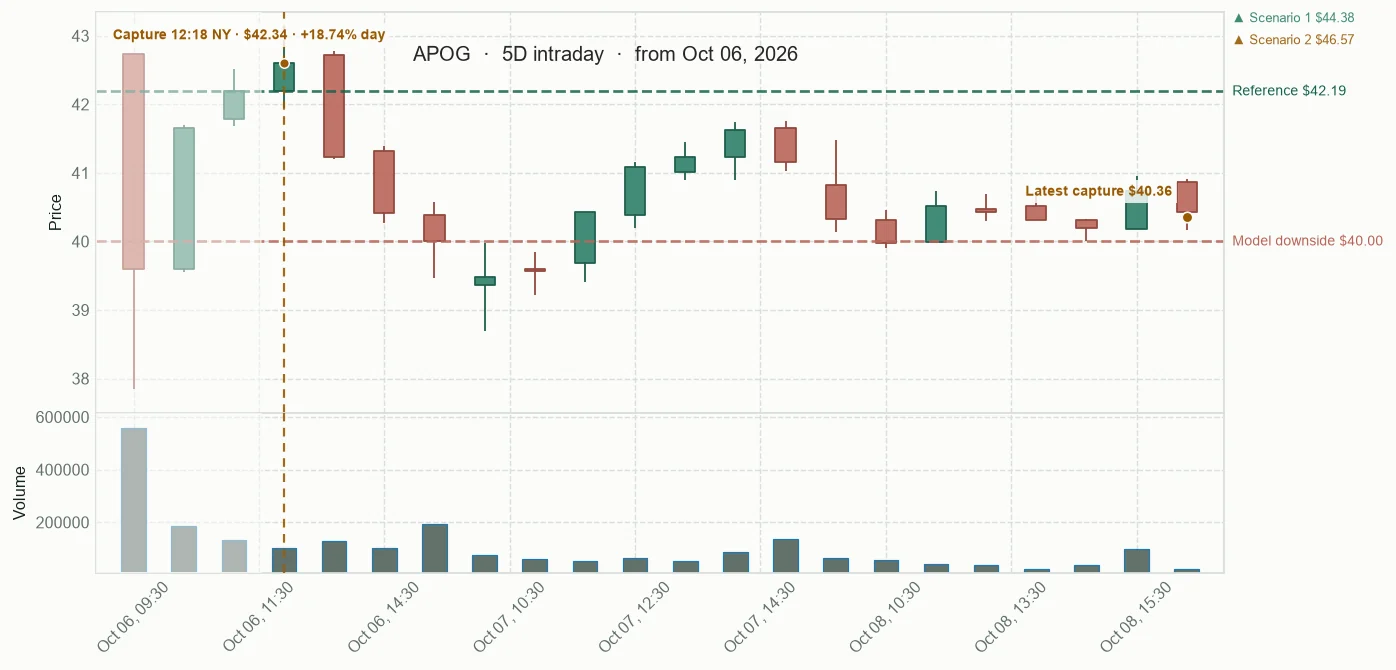
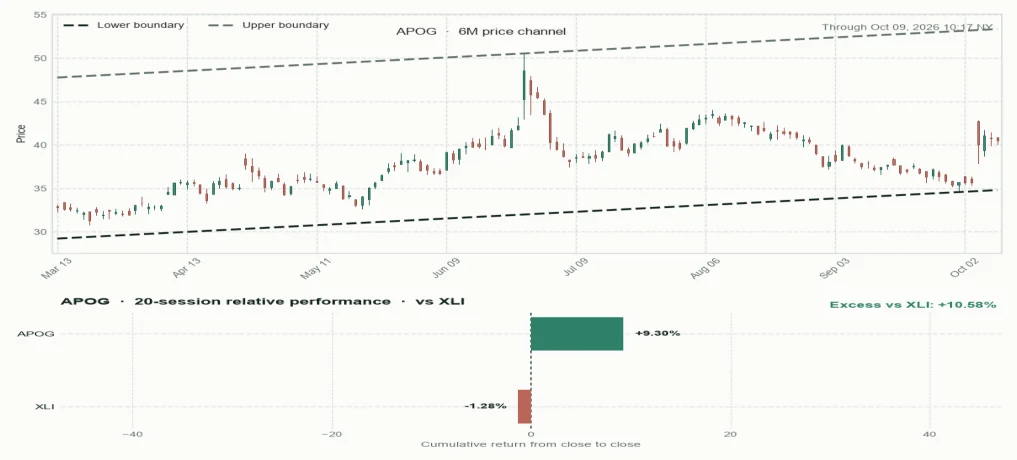
Initial thesisThe selection rests on reported earnings and higher FY2027 guidance, prior relative strength and a strong session response above the session’s volume-weighted average price. The active model gives LW higher positive-return estimates at the three, eight and fifteen-session horizons, and ranks it first versus APOG second among only four candidates with model results. Those estimates are context, not certainty: each historical adverse-MAE comparison uses eight cases, and APOG’s SEC-aware estimate relies on a September 1 prepared snapshot whose point-in-time validity is unestablished. This counterevidence moderates confidence without changing the selection.
Published at 💬
Broader Market Context The later market snapshot showed firm large-cap benchmarks alongside a weaker Russell 2000, while end-of-day breadth was unavailable. Day news paired a prolonged expansion with falling real hourly earnings; a tanker-supply warning and community-bank oversight discussion added separate risk and policy angles. Lower yields and dollar readings coexisted with mixed commodities, leaving the session without one simple macro explanation.
$40.84 +0.17% Today -3.20% base
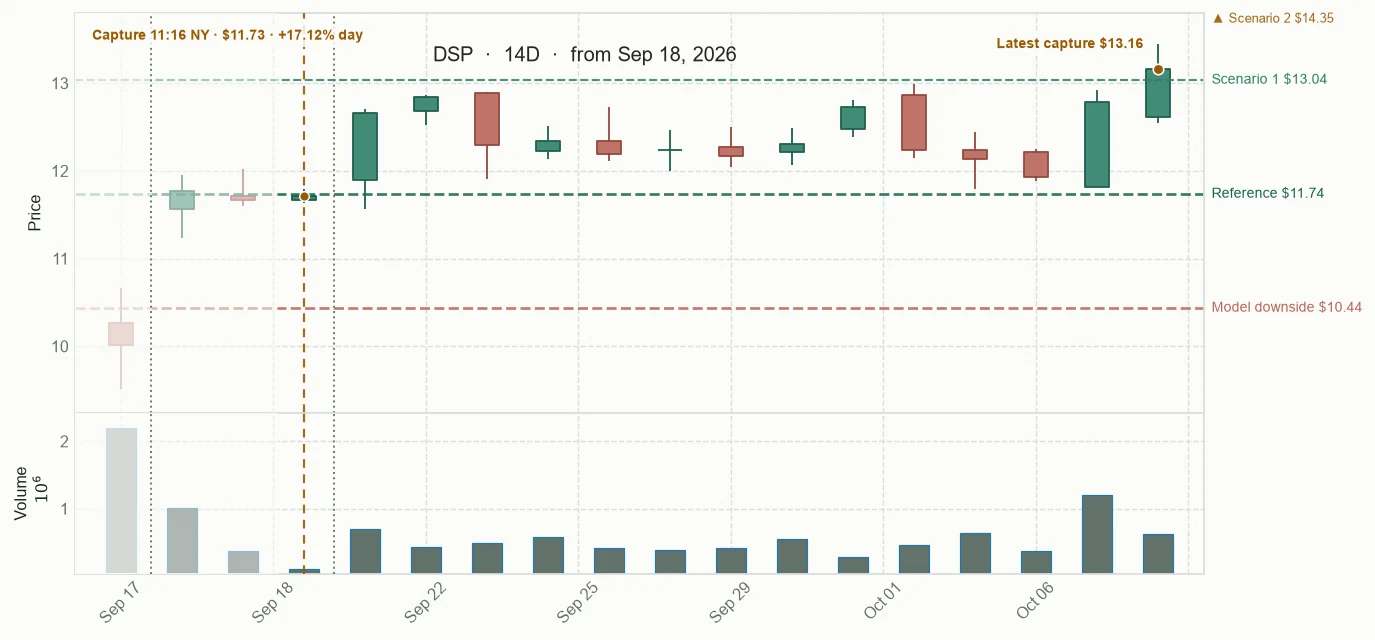
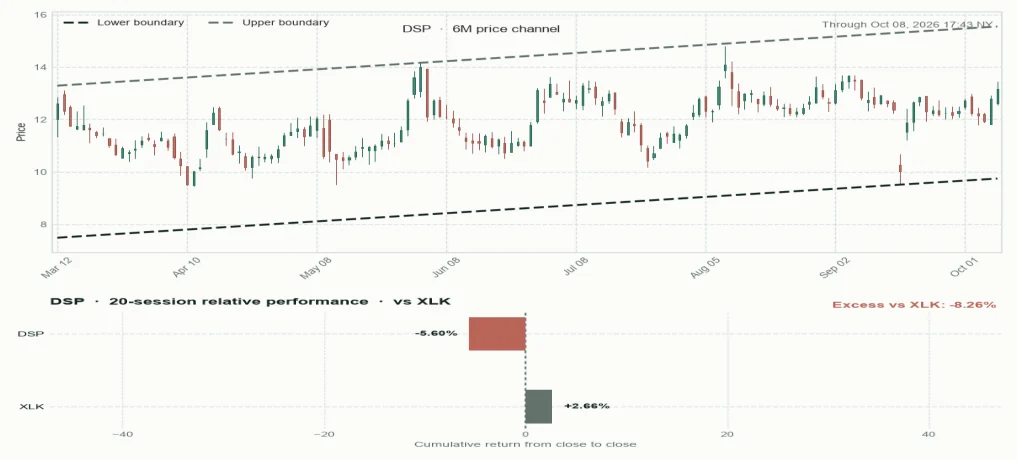
Initial thesisThe Desk currently selects DSP because the sealed primary filing documents the withdrawal of a planned 8.5 million-share secondary offering, while the stock recorded a +17.17% change on 4.71x average volume and held above 11.66 VWAP. Prepared SEC context for the quarter ended 2026-03-31 records $88.538 million revenue, a +25.333371082358937% revenue year-over-year change, -$455,000 net income and $2.925 million operating cash flow. The thesis remains conditional on continued VWAP retention and the absence of renewed dilution.
Published at 💬
Broader Market Context The day’s broad context was mixed and selective: large benchmarks were nearly steady, small caps were under pressure, the 10-year Treasury yield approached 5%, oil eased, and August industrial production was flat while manufacturing output fell. The public implication is narrower leadership and a higher need for company-specific confirmation. This Coffee adds context only and does not reopen or rescore the sealed DSP decision.
$13.03 -1.03% Today +10.95% base
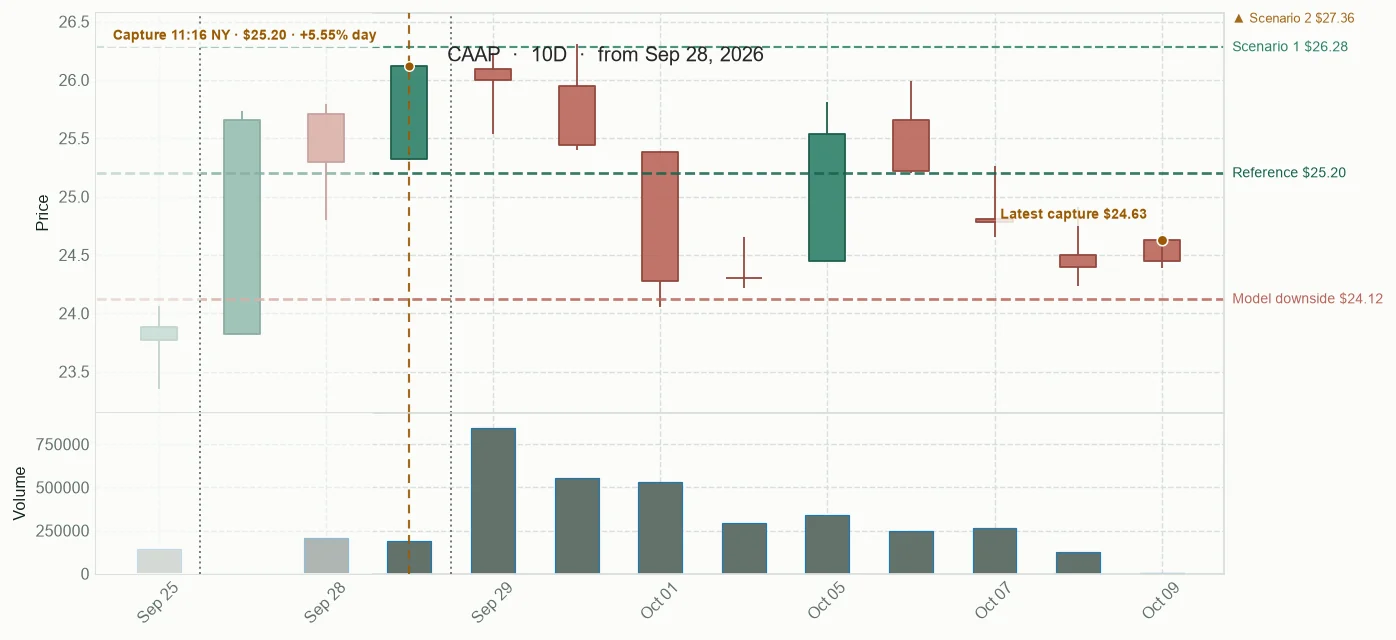
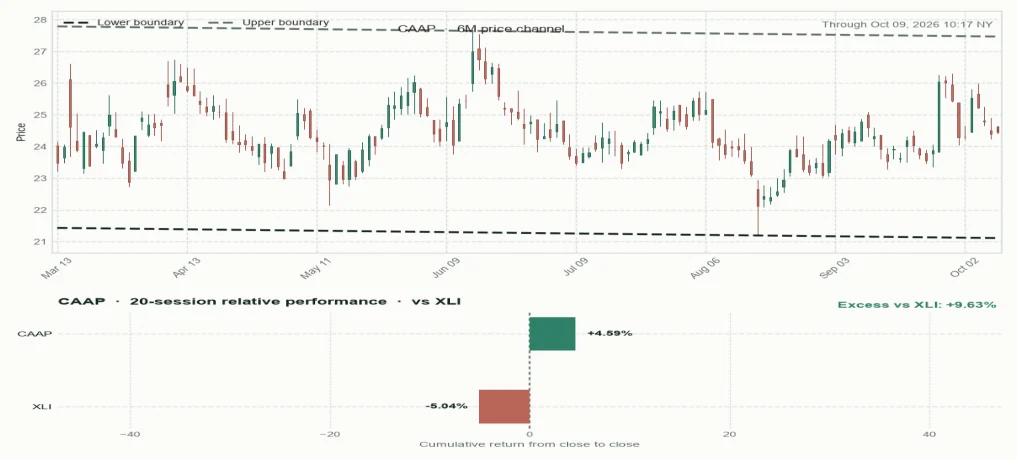
Initial thesisArgentina approved changes to CAAP’s airport concession arrangement tied to passenger growth and investment requirements. The earlier quote snapshot recorded a price of $25.205 and a change of +5.55%; a later pre-cutoff observation recorded a price of $26.00 and a change of +8.877727%. This one-session strengthening supports a current thesis but cannot establish persistence through S15. The revised terms’ effect on investment and cash flow remains unquantified.
Published at 💬
Broader Market Context The later market snapshot showed broad equity weakness alongside higher implied equity volatility and a higher Treasury yield. Earlier oil and rates reports add geopolitical and funding context, while the separate intraday breadth proxy must remain distinct from the snapshot’s unavailable breadth field. These conditions frame the day; they do not establish the economics of CAAP’s concession terms.
$24.46 +0.25% Today -2.94% base
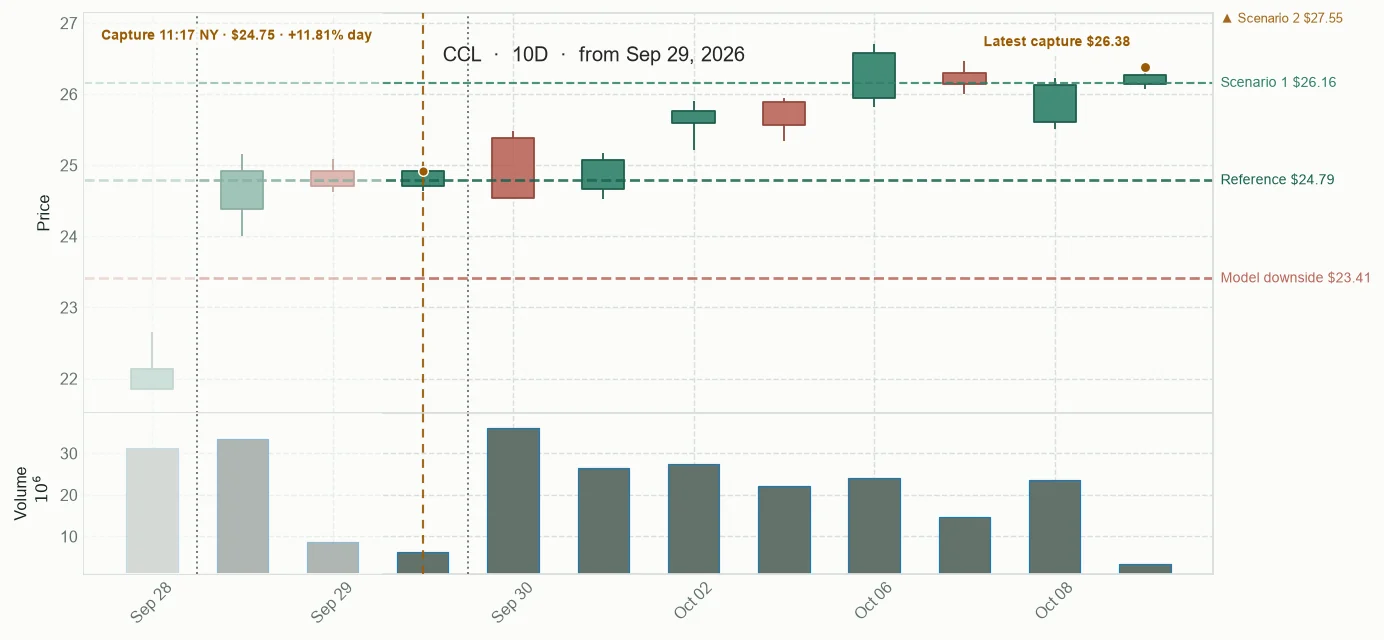
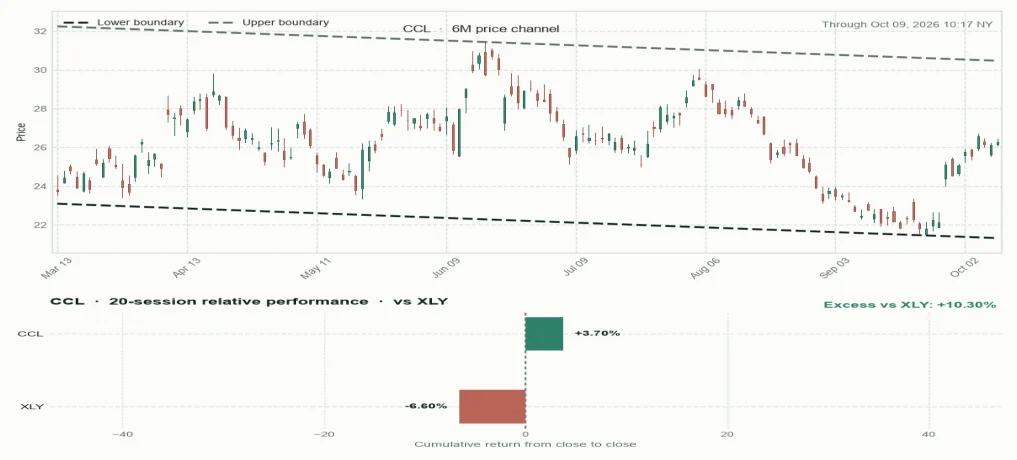
Initial thesisBoth companies have earnings catalysts. CCL's event move held near its high and its 20-session return was 11.23 percentage points ahead of its sector proxy. KMX's active model estimates are more favorable: estimated positive-return probabilities for sessions 3, 8, and 15 are 54.7%, 56.7%, and 52.8%, versus CCL's 47.0%, 46.9%, and 50.2%. The modeled adverse-MAE medians are also less negative for KMX at each horizon. Those comparisons use eight cases; MAE describes the worst interim adverse move from the entry reference, not the final return. A separate audit-only H15 historical-dispersion output favors KMX as well, but it is contextual and not a selection score. CCL remains the current choice because its supplied event-session tape and sector-relative record are stronger. Confidence is reduced, and follow-through remains the key test.
Published at 💬
Broader Market Context The day’s market snapshot leaned weak, with broad participation also soft in its covered intraday basket. Other signals diverged: August labor-market measures changed little, mortgage scoring access broadened, and electricity investment and grid constraints remained a structural theme. Oil and policy headlines add uncertainty, but the shared context does not quantify any company’s demand, financing sensitivity or fuel costs.
$26.29 +0.61% Today +6.05% base
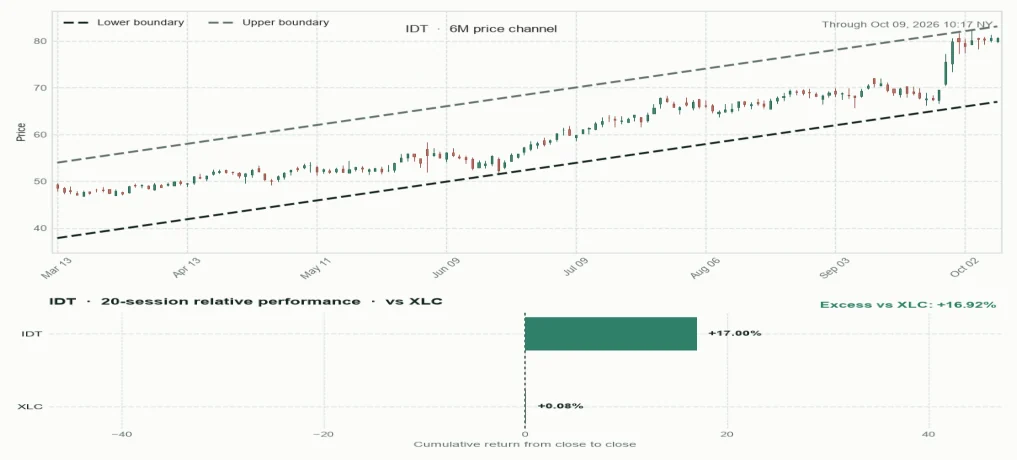
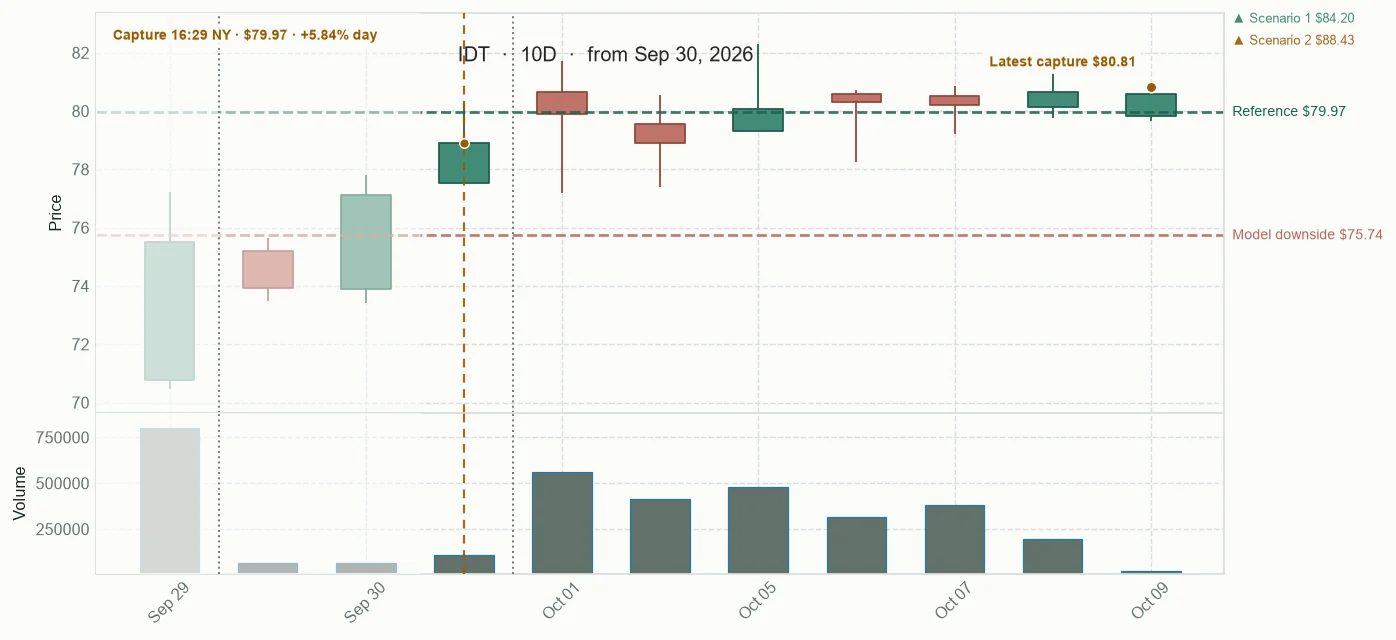
Initial thesisIDT remains the Try of the Day. Its recent results reported year-over-year growth in gross profit, operating income and adjusted EBITDA; its September 30 quote snapshot reported a 5.84% change on above-average volume. The separate intraday signal placed price above VWAP. The EPS miss, extended price and unavailable horizon forecasts remain material limits.
Published at 💬
Broader Market Context The early snapshot showed modest gains across major indexes, but the closing picture was mixed: the S&P 500 and Russell 2000 ended lower while the Nasdaq Composite edged higher. Oil, inflation and rates remained cross-currents, and validated breadth was unavailable. IDT's operating results belong to the company-specific story; they do not turn the wider session into a single market narrative.
$81.52 +1.08% Today +1.94% base
Initial thesisThe revised $123 all-cash offer produced a sharp, high-volume repricing. The evidence supports following the transaction status, but does not establish that it will close or that the share price has a favorable 15-session path.
Published at 💬
Broader Market Context September payroll growth was weak and prior months were revised down, while the supplied major indexes rose and the VIX fell. The 10-year yield rebounded into the close, and breadth data was unavailable. The mixed backdrop frames the day but does not explain a company-specific transaction repricing.
$119.77 +0.58% Today -1.29% base
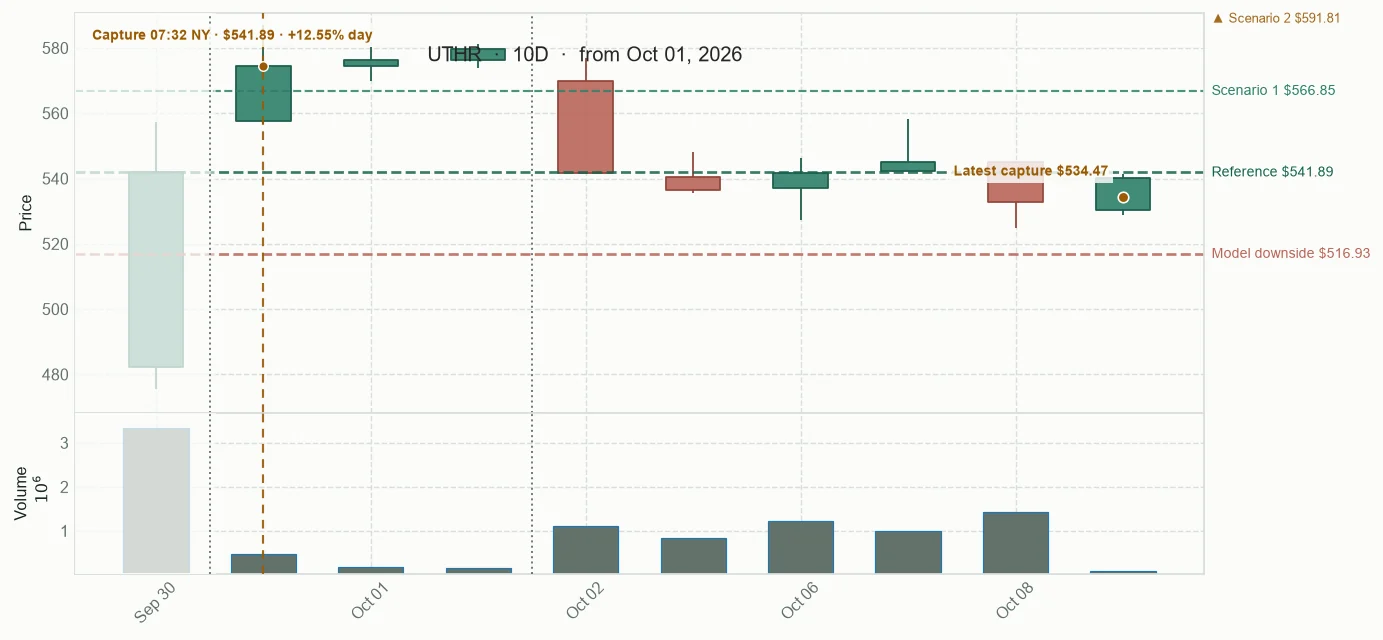
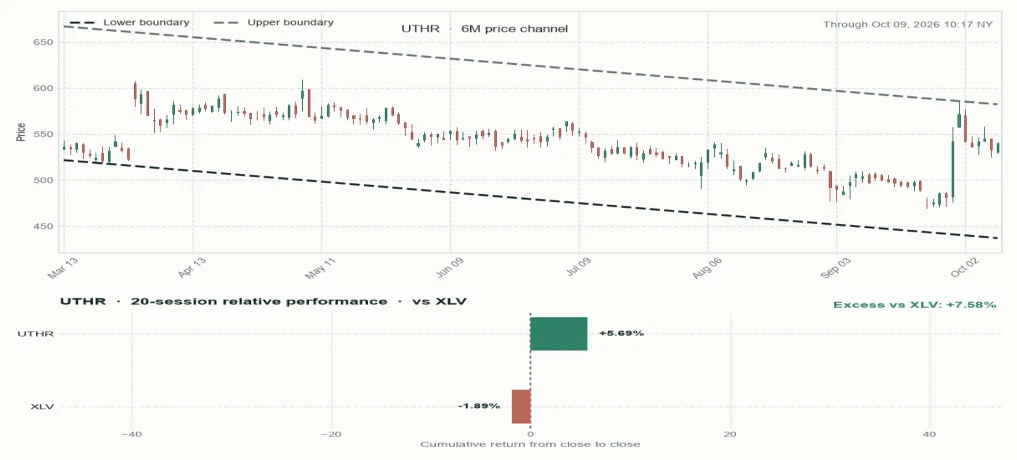
Initial thesisUTHR remains a research-only Raw Try based on the September 30 two-claim court finding and the pending judgment language. The active H15 adverse-MAE estimate is P10 -19.968165%, P50 -8.252136% and P90 -0.738464%; it describes a possible interim adverse move, not the return at session 15. It includes SEC context whose point-in-time validity is unverified. The sealed chart archive contains no views for the eight compared candidates, so their market structure is assessed from the supplied tabular evidence only. These limitations reduce confidence without changing the selected identity or resolution.
Published at 💬
Broader Market Context The dated market snapshot was mixed: the Nasdaq 100 was firmer while the S&P 500 and Russell 2000 were lower, and volatility rose modestly. A separate end-of-day breadth reading leaned negative, but its intraday proxy was unavailable. Inflation and bond headlines, oil and Iran coverage, and cross-asset moves describe different instruments and capture windows; together they frame an uneven backdrop without explaining any individual company outcome.
$549.13 +3.07% Today +1.34% base
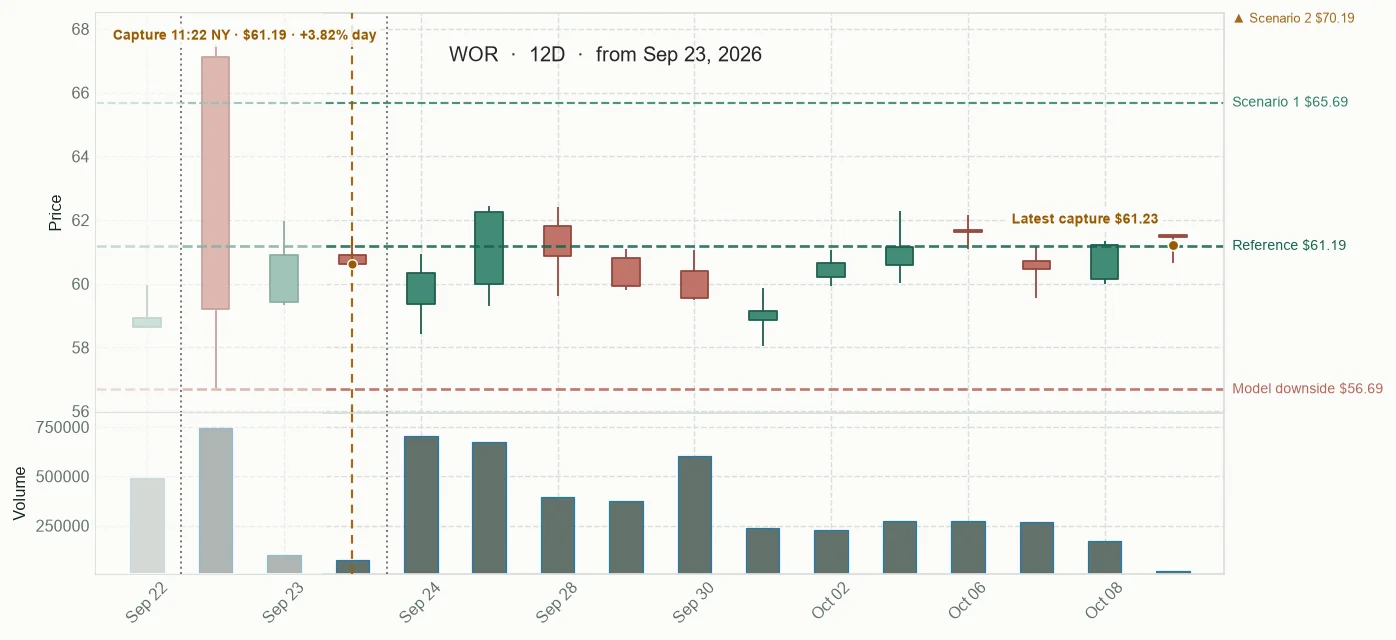
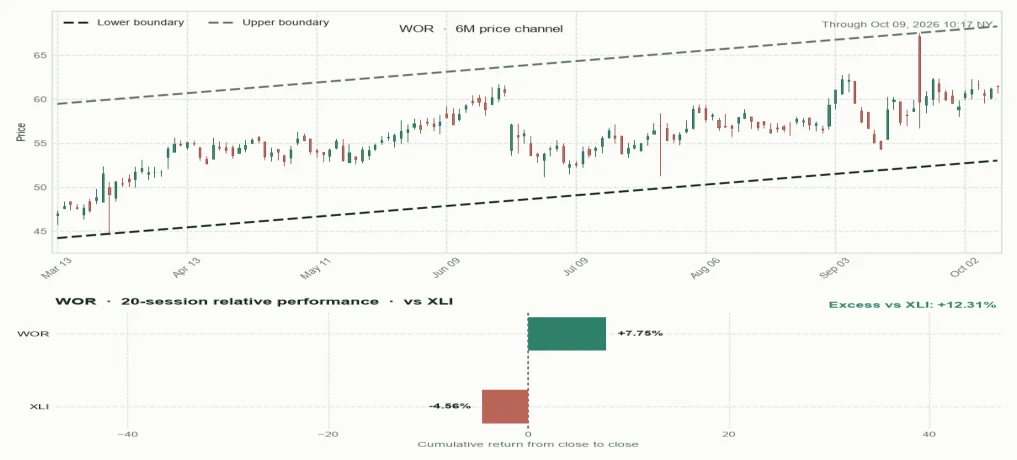
Initial thesisWorthington's reported fiscal 2027 first-quarter sales grew 13% year over year, and adjusted EPS exceeded the supplied estimate. Its 20-session return also exceeded the Industrials proxy. The premarket rise faded by the decision cut, so the next fresh session is the key continuation check.
Published at 💬
Broader Market Context Resilient flash business surveys met a weaker equity tape, firmer rates and dollar, and unsettled energy and geopolitical headlines. The intraday breadth proxy leaned negative, but end-of-day breadth was unavailable and the market snapshot had aged past its freshness window by the cutoff. Worthington’s results provide a company-specific data point within those cross-currents, not a market-wide explanation.
$62.12 +1.48% Today +1.53% base
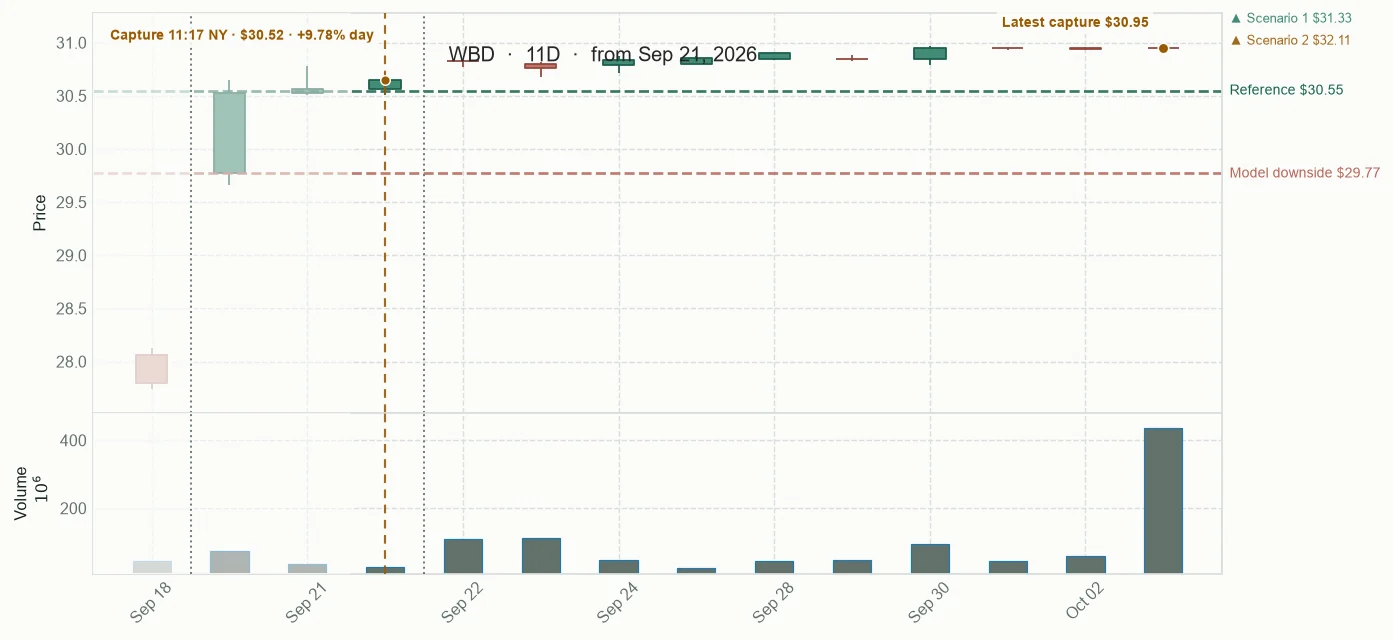
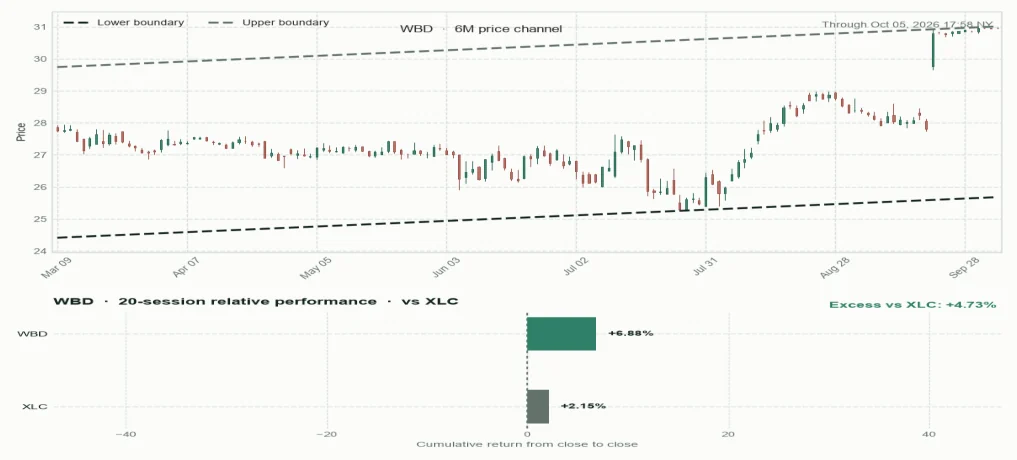
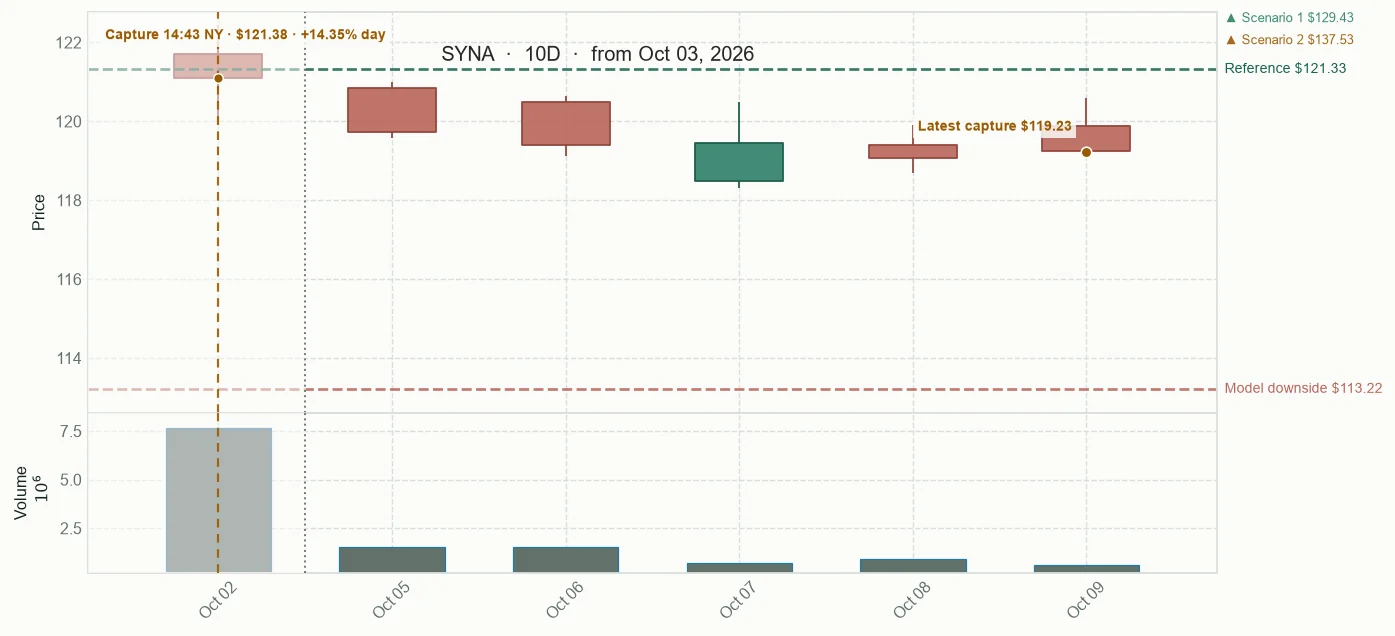
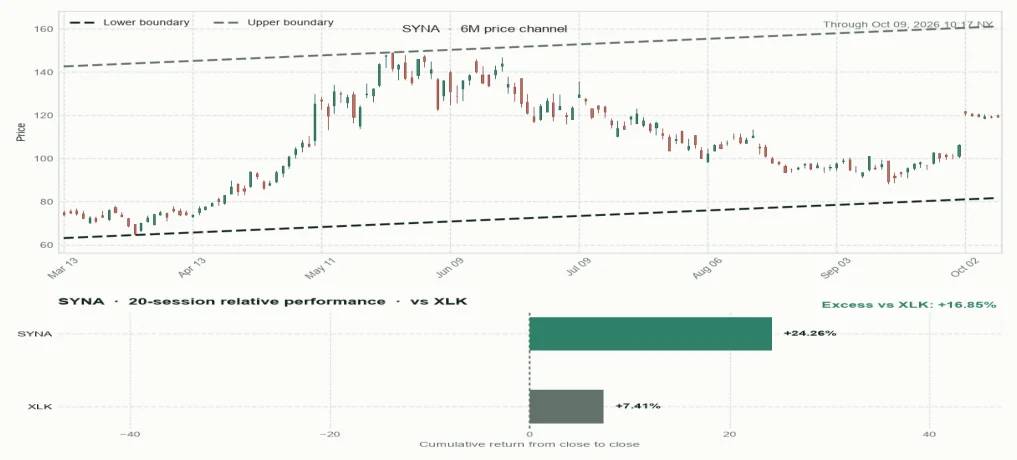
Initial thesisThe Desk currently selects WBD because a specific merger-settlement mechanism is supported by exceptional participation, above-VWAP structure and a strengthening trajectory. The selection remains conditional on continued transaction progress and price confirmation.
Published at 💬
Broader Market Context The Coffee reviewed the sealed day context as a selective risk-supportive session rather than a uniform market advance. It connected partial breadth, geopolitical cost uncertainty, rates, company history and the reported transaction context without reopening or changing the WBD decision.
$30.95 +0.00% Today +1.31% base

The coverage archive

Beyond observation

Not every published episode remains under active observation. Once an episode is closed, or belongs to the earlier legacy record, it is preserved here for reference.

This is where you can explore the coverage that came before: what was published, what changed, and how each episode eventually concluded.

View full coverage →

INGM · Ingram Micro Holding Corporation

TryFinally
Initial thesis

The panel currently selects Ingram Micro as Try of the Day. A verified secondary offering and concurrent repurchase produced a concrete supply test, and the sealed path stayed positive through five observations. The case remains vulnerable to distribution, short-interest pressure and a loss of the offering-area VWAP.

Relevant update at

At session 15, Ingram Micro's tracked return was +4.78%. The original thesis tested whether an announced, conditional 625,000-share repurchase could absorb a 13,125,000-share sale near .23. The result was positive, but the record does not verify that the repurchase completed or absorbed the offering; many follow-ups stayed below the reference. An October 5 after-hours mark of .58 came after the tracking horizon and was 3.23% below that day's regular close. No separate extended-hours quote or final RSI, trend or range readings were supplied. Tracking is closed.

Committee read

Base $27.25 · Close $28.50

Observed return by session
S+1-1.29%S+5-1.95%S+10-0.81%S+15+4.78%

AVAV · AeroVironment, Inc.

TryFinally
Initial thesis

The latest ordered AVAV prices are approximately 154.50-154.55 against the 153.21 VWAP reference, implying an immediate cushion of approximately 0.8-0.9%. These captures are not synchronous. MDA’s active H15 model context is 53.7% versus AVAV’s 50.4%, with a less adverse sealed H15 tail; both are bounded context from eight comparable cases, not a selection rule. AVAV’s larger-frame weakness, execution risk and need for dated backlog or program-conversion evidence remain explicit.

Relevant update at

At session 15, AVAV’s completed tracked return was -10.86%, after a best recorded gain of +6.73% and a worst excursion of -12.13%. The original thesis tied an issuer-supported defense-demand story to future orders, revenue and deliveries, with strong initial participation as an early check. Price crossed the stated $145.76 downside reference on September 29, and the public record never supplied dated proof that backlog converted into orders or deliveries. This closes the market test; it does not disprove that defense demand existed. October 5 after-hours fields conflict: one quote lists $139.84 while attached market data lists $139.30. Final RSI, trend and 52-week-position readings were unavailable. No further tracking follows.

Committee read

Base $157.40 · Close $140.31

Observed return by session
S+1-6.79%S+5+3.80%S+10+0.73%S+15-10.86%

SIG · Signet Jewelers Limited

TryFinally
Initial thesis

SIG is currently selected because its primary earnings event, strong participation and above-VWAP reaction form the clearest current mechanism-to-tape link in the compared set. The thesis remains conditional because the stock is extended, near its 52-week high and still requires confirmation beyond the initial repricing.

Relevant update at

At the completed fifteenth session, Signet’s tracked return was +3.58%. The original thesis linked a profit beat, a raised full-year outlook and an announced $125 million buyback to a sharp earnings-day repricing, then asked whether demand would persist. The result stayed positive, but it fell from +5.59% at session 14 and the record never confirmed durable price structure or proved that the company event alone caused the return. A separate October 5 after-hours quote was $100.89 as of 21:04 Atlantic/Canary, about +2.12% against the publication reference; that later mark does not replace the session-15 result. Final RSI, trend and 52-week-position readings were unavailable. Tracking is closed.

Committee read

Base $98.80 · Close $102.33

Observed return by session
S+1-1.10%S+5+4.20%S+10+1.98%S+15+3.58%

NPWR · NET Power Inc.

TryFinally
Initial thesis

NPWR is the strongest comparative Try of the Day because the review data combines an orderly breakout, above-VWAP trade, meaningful participation and a specific earnings-linked strategic pivot. It is not the least risky name; it is the case with the clearest next test and falsifier after the alternatives were challenged.

Relevant update at

NPWR tracked loss widened 3.27 points to -9.55% as the current capture fell 5.76% to $1.80, 2.70% below VWAP on 0.80x average volume. The SEC-linked strategic pivot remains a specific question, but the $2.00 breakout test has moved further away: price is below the reference, participation is ordinary, and no structure is confirmed, so the market has not yet supplied evidence of sustained demand.

Committee read

Base $1.99 · Close $1.80

Observed return by session
S+1-2.01%S+5-10.55%S+10-4.52%S+15-9.55%

The framework behind the record

Read the method behind the conclusion.

Coverage is easier to trust when the route to the conclusion remains visible: the evidence, the panel conversation and the limits of what can be inferred.